Popis
Repayment plans are compared by monthly payment alone, which hides total cost, forgiveness eligibility and what happens if income changes.
Repayment plans are compared by monthly payment alone, which hides total cost, forgiveness eligibility and what happens if income changes.
This is a complete system to choose a student loan repayment plan and keep the work under control: a
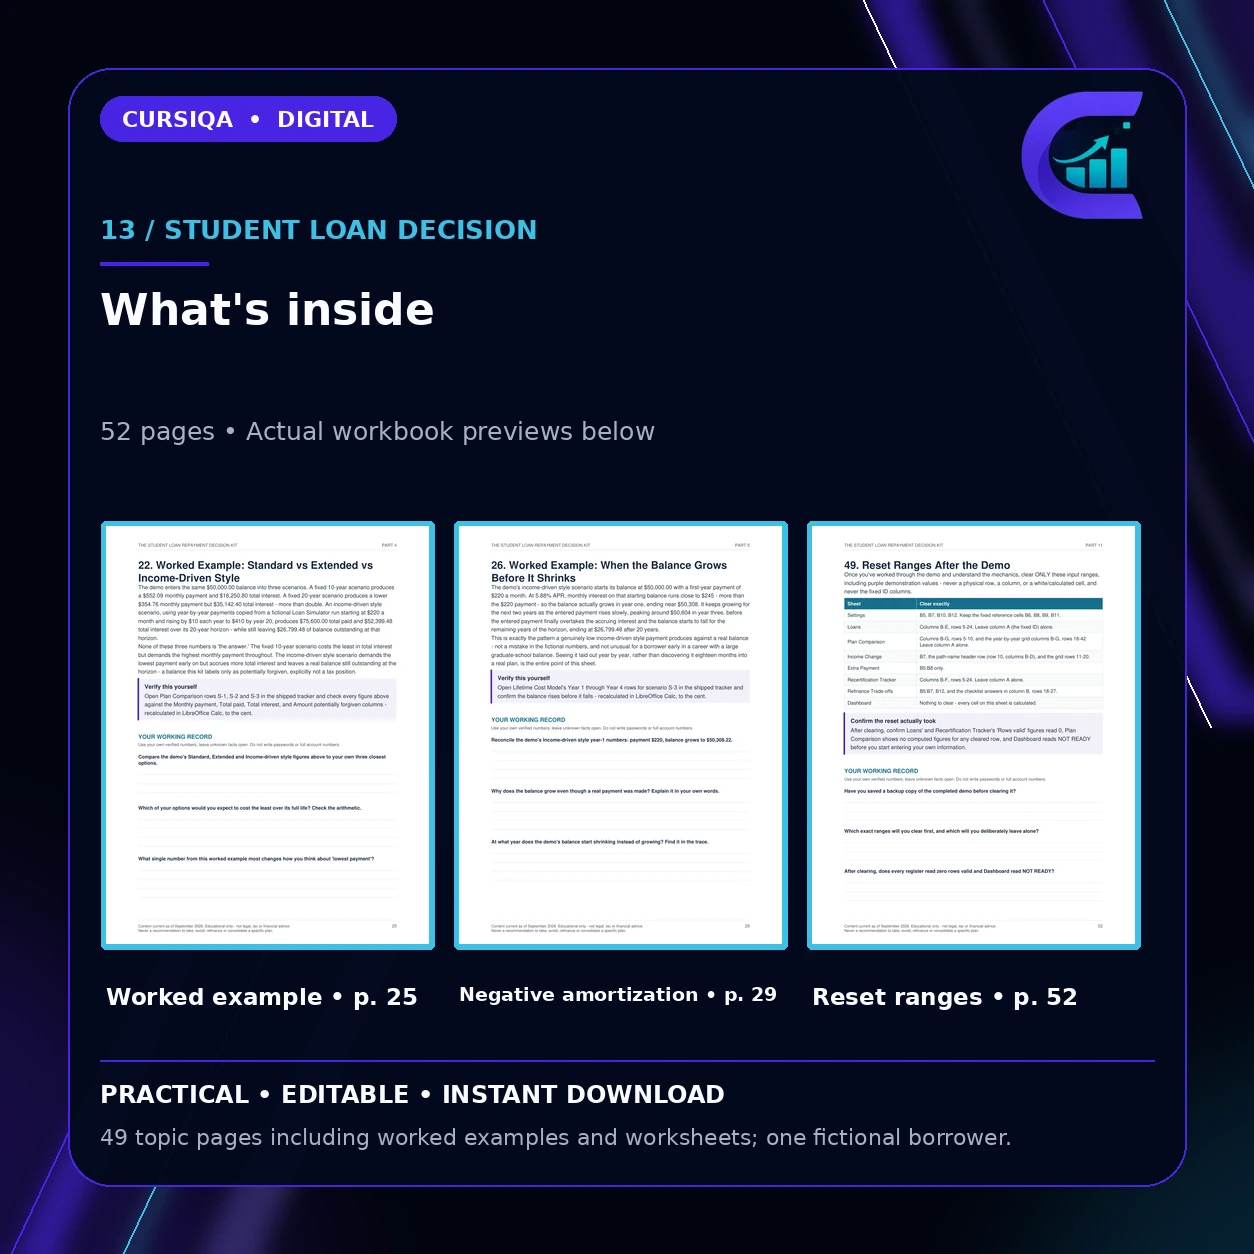
52-page workbook that walks through the method, and a
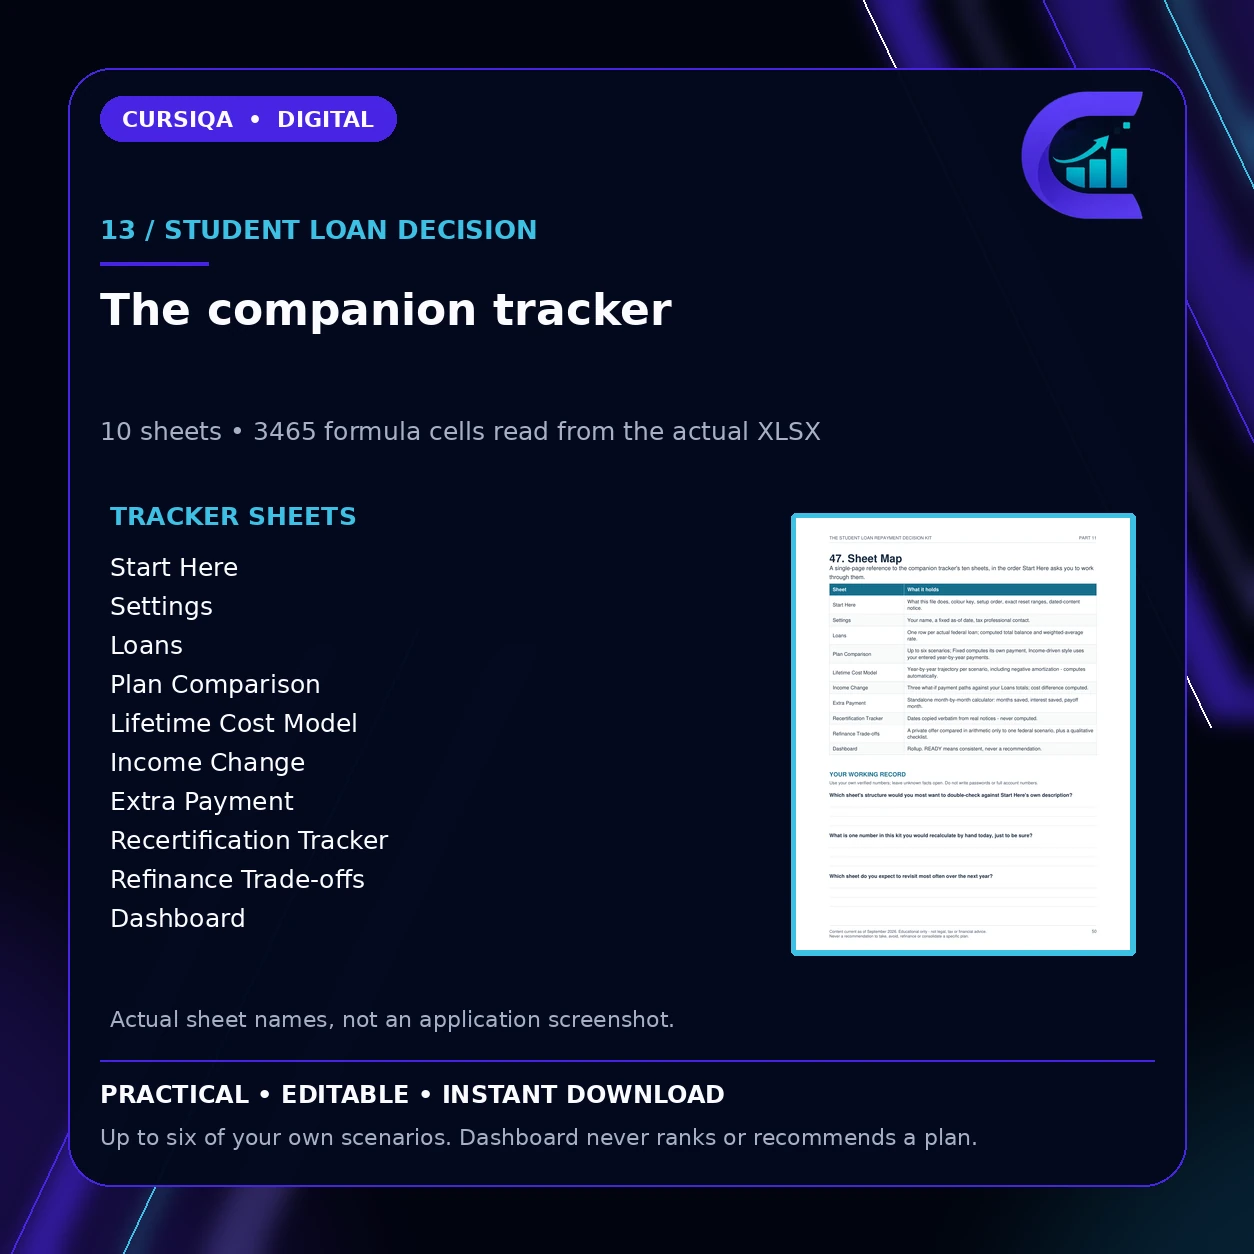
10-sheet tracker that does the counting for you.
Who this is for
US borrowers choosing between repayment plans or considering consolidation.
The workbook
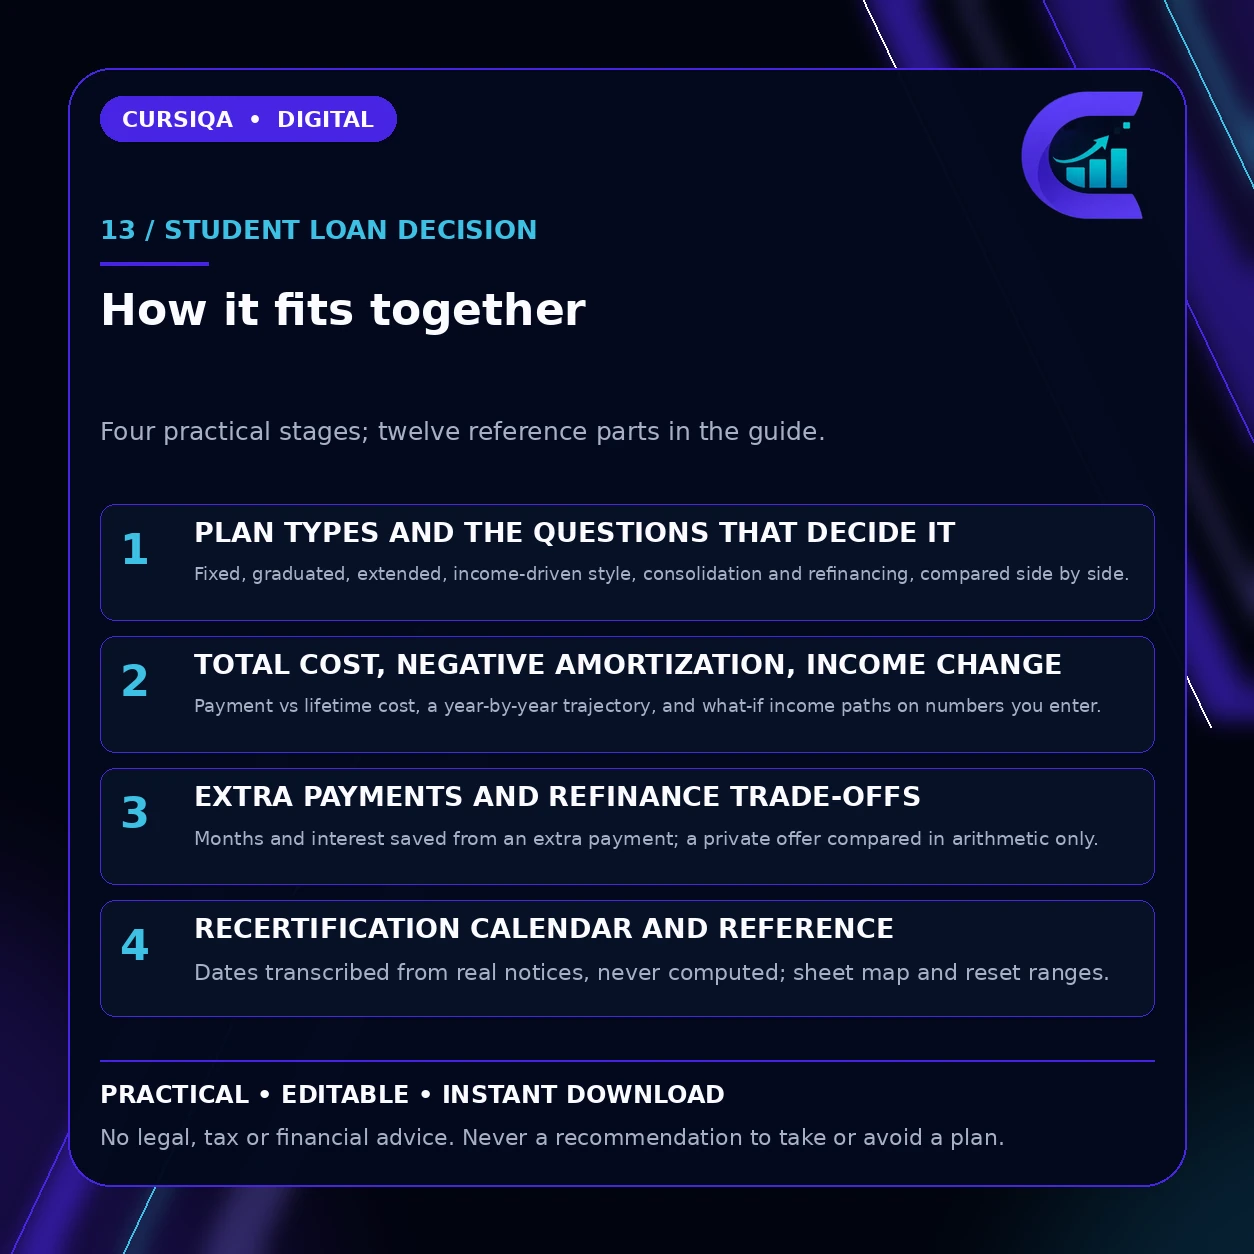
Plan types explained side by side, the questions that decide it, what changes eligibility, refinancing trade-offs, recertification calendar.
The tracker
Total-cost comparison across plans, payment-vs-lifetime-cost model, extra payment impact, recertification tracker. 3465 formulas calculate as you fill it in, so
you are reading results rather than building a spreadsheet.
What you get
- 52-page PDF workbook (15,508 words)
- 10-sheet Excel tracker with 3465 formulas,
Excel-format .xlsx, recalculated and mutation-tested in LibreOffice Calc. Microsoft Excel desktop and Google Sheets import were not verified; all formulas are visible and unlocked, with no macros or external connections - Read-me-first guide so you know where to start
- Instant download, 162 KB, yours to keep
What this is not
Educational arithmetic and organization only, not legal, tax, investment or financial advice, and never advice to take, avoid, refinance or consolidate a specific plan. Federal student loan rules change; legislation enacted in 2025 phases in changes from 2026, and this content is dated September 2026. The kit states no income-driven formula, percentage, poverty-guideline multiple, forgiveness year count or plan availability as fact: you read those from StudentAid.gov, your own Loan Simulator run or your servicer and enter them. Recertification dates are transcribed from your own notices, never computed. A potentially forgiven balance is arithmetic only, not a tax position; ask a tax professional. Interest is modelled as simple monthly accrual without capitalization events; fixed input ranges do not auto-expand. The supplied demonstration borrower is explicitly fictional.